/
•
•
Detailed stories on technology startups, business and economic current affairs.

Editor's note: Facebook just announced the launch of a new payments feature a couple of days ago in the US—Facebook Pay. It’s essentially a rebranding and consolidation of existing in-app payments on Facebook and Instagram (for shopping, donations, etc.) and a peer-to-peer transfer option in Messenger. To begin with, Facebook Pay will let users send and receive money, and also pay for things, on Facebook and Messenger in the US, with more countries to come eventually, and an integration across Facebook’s entire portfolio of apps, including Instagram and WhatsApp. This is interesting for two reasons. First, everybody wants to get into digital payments, everywhere in the world. From pure-play digital banks to telcos to messaging apps to ride-hailing companies. The pitch is always convenience for the user and data for the business, which theoretically lets you get deeper into finance with lending, as well as strengthen existing targeted advertising systems. Looking at US tech companies, the cheerfully unprofitable Paypal-owned Venmo has become a verb for peer-to-peer transfers, with some competition from Square Cash, Google Pay and Apple Pay (and now Facebook Pay). …
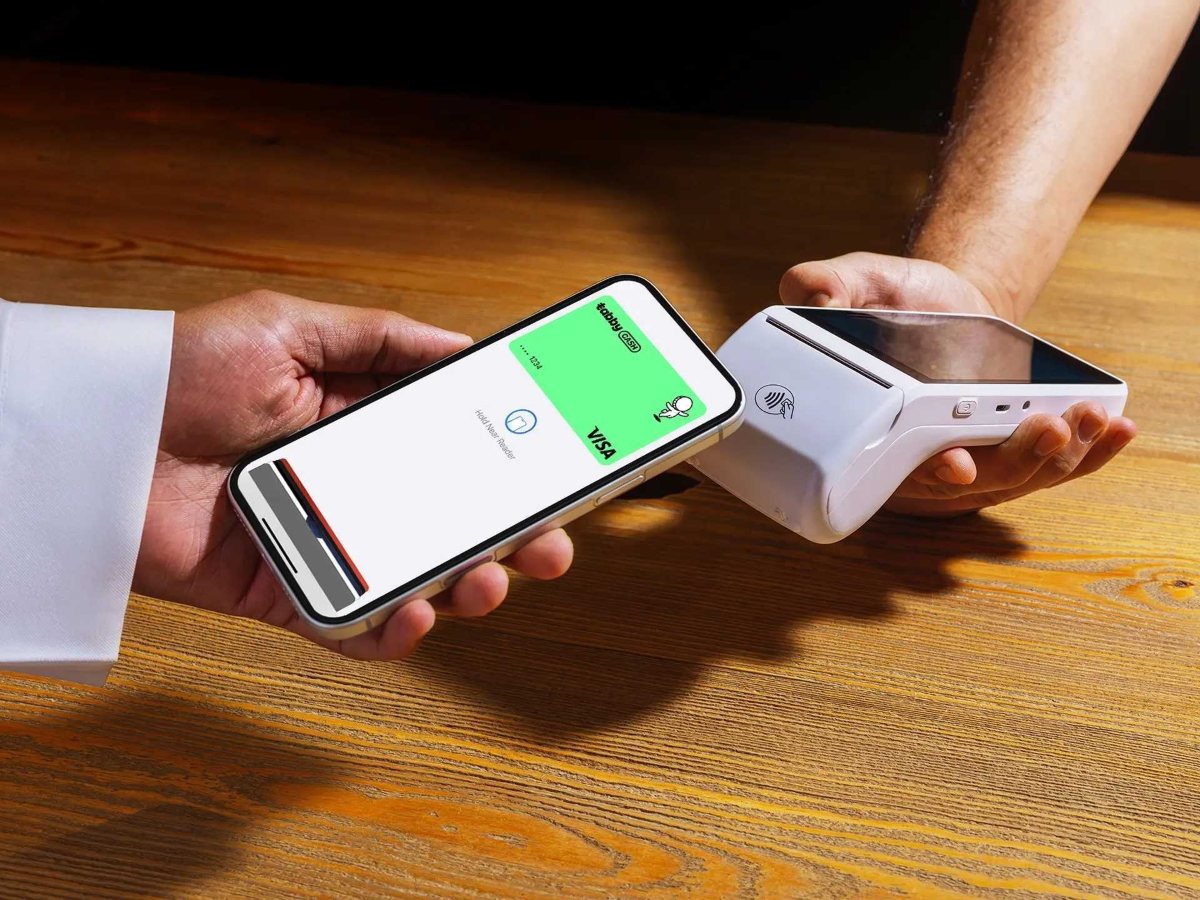
Editor's note: Facebook just announced the launch of a new payments feature a couple of days ago in the US—Facebook Pay. It’s essentially a rebranding and consolidation of existing in-app payments on Facebook and Instagram (for shopping, donations, etc.) and a peer-to-peer transfer option in Messenger. To begin with, Facebook Pay will let users send and receive money, and also pay for things, on Facebook and Messenger in the US, with more countries to come eventually, and an integration across Facebook’s entire portfolio of apps, including Instagram and WhatsApp. This is interesting for two reasons. First, everybody wants to get into digital payments, everywhere in the world. From pure-play digital banks to telcos to messaging apps to ride-hailing companies. The pitch is always convenience for the user and data for the business, which theoretically lets you get deeper into finance with lending, as well as strengthen existing targeted advertising systems. Looking at US tech companies, the cheerfully unprofitable Paypal-owned Venmo has become a verb for peer-to-peer transfers, with some competition from Square Cash, Google Pay and Apple Pay (and now Facebook Pay). …
The newly announced levy on UPI payments undermines the very foundation of using digital payments for stock market investing. Brokers are in a tizzy.

India’s second-largest brokerage by active clients wants to handle IPOs as a merchant banker. But gaining a foothold in the highly competitive sector is easier said than done.
Influence cannot be manufactured through diaspora networks, carefully branded events or political donations. It requires honesty and credibility.
The newly announced levy on UPI payments undermines the very foundation of using digital payments for stock market investing. Brokers are in a tizzy.
India’s second-largest brokerage by active clients wants to handle IPOs as a merchant banker. But gaining a foothold in the highly competitive sector is easier said than done.
Influence cannot be manufactured through diaspora networks, carefully branded events or political donations. It requires honesty and credibility.