/
•
•
Detailed stories on technology startups, business and economic current affairs.
The proprietary trading firm’s guilt is as obvious as its innocence, depending on who you ask. However, the truth often lies in the grey areas. Many answers are needed from both Jane Street and SEBI.

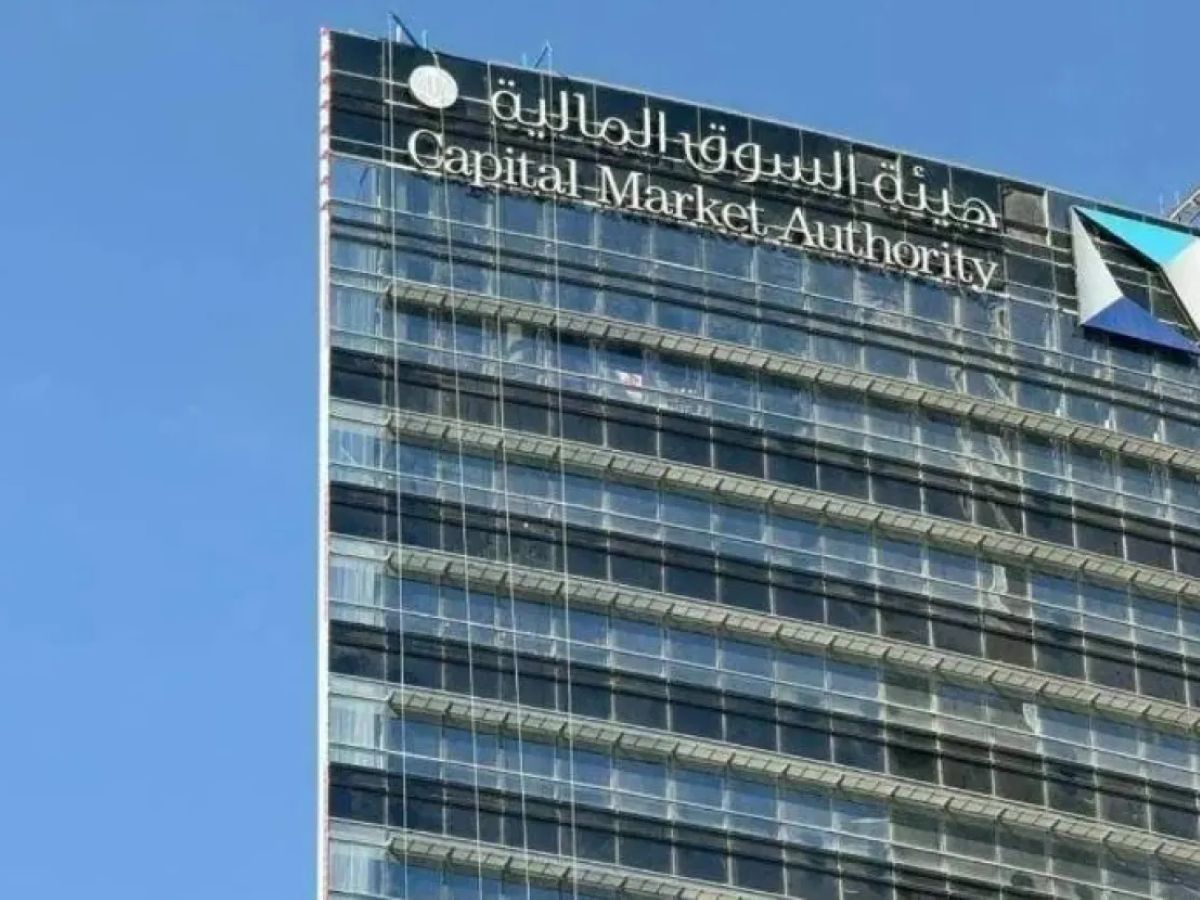
It has been over two weeks since the Securities and Exchange Board of India’s seminal interim order on Jane Street was issued. The most significant—and for some, surprising—development in this time has been Jane Street’s quiet acquiescence last week in paying up the “unlawful gains” of nearly Rs 4,844 crore ($567 million) into an escrow account, as demanded by the market regulator. And yesterday, Jane Street was back to trading.
Why the surprise? Given that Jane Street was “beyond disappointed” by what it called SEBI’s “extremely inflammatory” accusations, some expected the secretive Wall Street proprietary trader to challenge the interim …
Thinly traded listed entities have long served as breeding grounds for stock manipulation, hurting investors. The regulator, the NSE and BSE now want to fix things by focusing on efficient delisting.
A month on, CAS has only amplified volatility, manipulation and confusion rather than containing them.
The regulator’s shift to an auction-based close was meant to curb manipulation and mirror global markets. Instead, it has run into thin participation that is only amplifying distortions and volatility.