/
•
•
Detailed stories on technology startups, business and economic current affairs.
The central bank’s directive to intensify scrutiny of customers onboarded through Central KYC or DigiLocker seems to be at odds with the government’s Digital India mission.


The Reserve Bank of India recently made significant changes to know your customer rules, tightening customer authentication by banks, NBFCs and payment companies. The objective seems to be to rein in fraud and aid the government’s ongoing crackdown on money laundering.
In two separate amendments to the KYC master directions—first on 28 April and then on 4 May—the central bank introduced new rules to ensure “meticulous compliance” by regulated entities while vetting customer identity.
Curiously, it has also flagged as “high-risk” all accounts opened by vetting customers through the government’s Central KYC and DigiLocker facilities. This has left the industry …
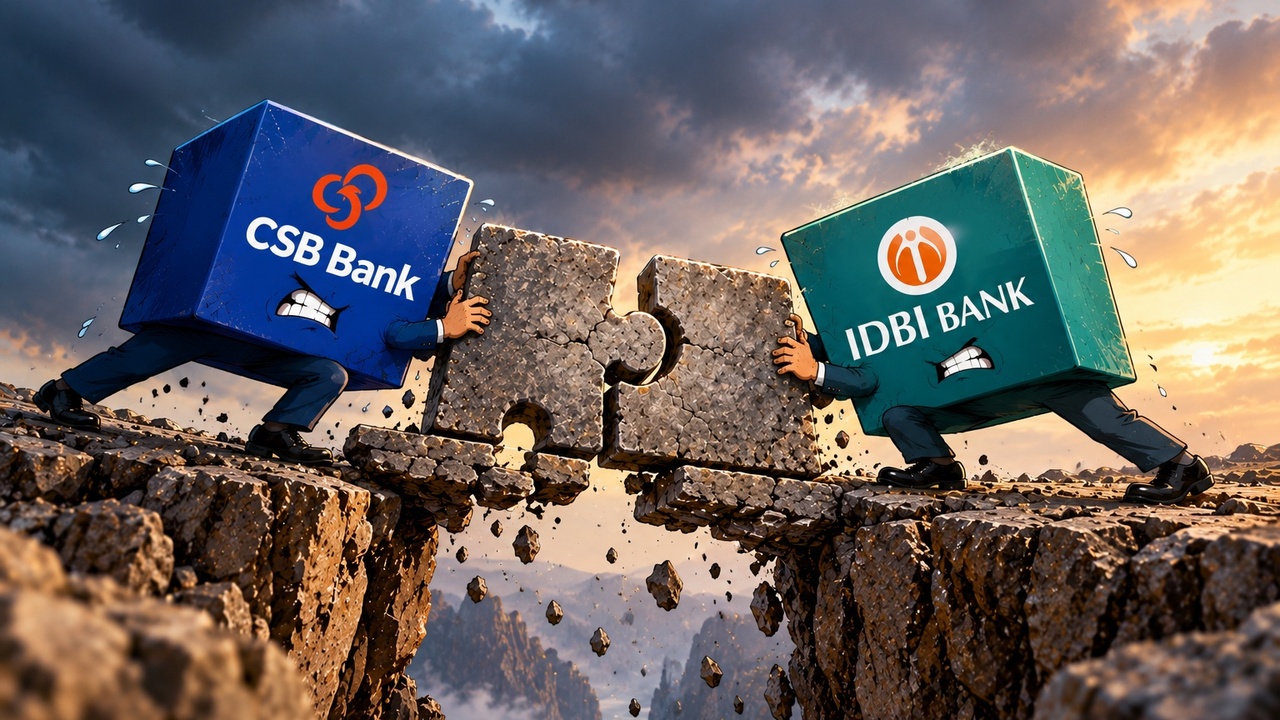
The acquisition of IDBI Bank puts his Fairfax smack dab in the middle of the RBI’s rules on bank ownership. It must now decide whether to sell CSB Bank or merge the two lenders, neither of which will be easy.
Lenders stand to gain a lot more than borrowers in the current challenging market environment
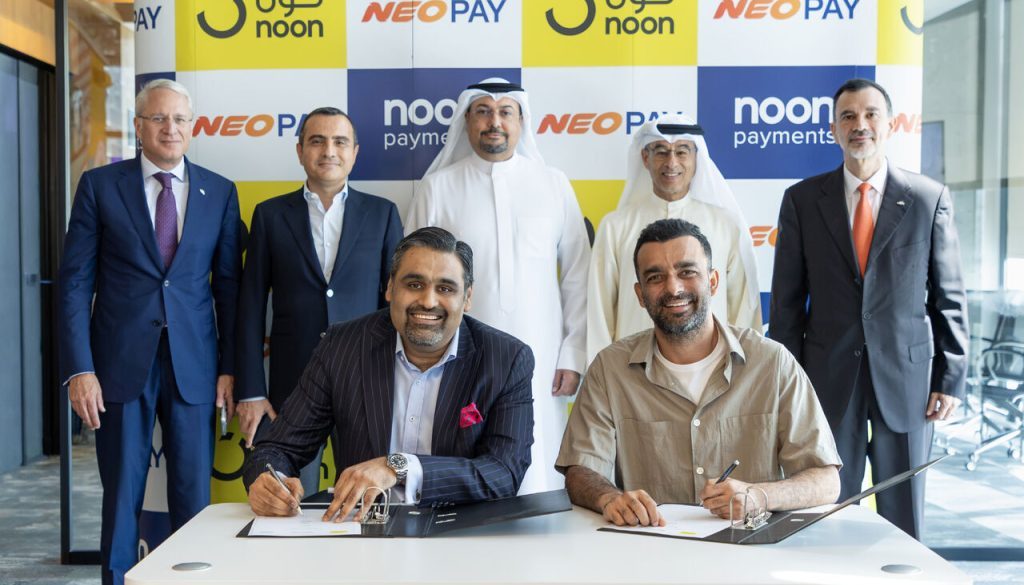
A local fintech deal to consolidate operations, feedback on Saudi Arabia’s proposed IPO rules, and Ras Al Khaimah’s casino economy.