/
•
•
Detailed stories on technology startups, business and economic current affairs.
Franklin Templeton's unpaid brokerage in the six debt schemes is another unsolved puzzle. The futility of the legal fight between Tata Group and Mistry clan.

Editor's note: If you thought there were no more skeletons left in Franklin Templeton India’s closet, you need to think again. Having written a fair bit on the unethical behavior of its top management and fund managers in the run-up to the closure of its six debt mutual fund schemes, even I thought I was done with the asset management company for a while. But there is some new information that’s come to light. We will get to it in a bit. I’d like to state at the outset that the Rs 15,000-odd crore which has come into Franklin Templeton’s six wound up schemes through prepayments, maturities and sales can, by no means, be discounted. However, the narrative needs some course correction here. Returning money to investors without haircuts is not a favour but the bare minimum expected of an AMC. And, by no stretch of imagination, does it give it a clean bill of health with regard to mismanagement and unethical behavior. The other big event of the past fortnight from this newsletter’s point of view was the culmination of the …
Franklin Templeton's unpaid brokerage in the six debt schemes is another unsolved puzzle. The futility of the legal fight between Tata Group and Mistry clan.
Editor's note: If you thought there were no more skeletons left in Franklin Templeton India’s closet, you need to think again. Having written a fair bit on the unethical behavior of its top management and fund managers in the run-up to the closure of its six debt mutual fund schemes, even I thought I was done with the asset management company for a while. But there is some new information that’s come to light. We will get to it in a bit. I’d like to state at the outset that the Rs 15,000-odd crore which has come into Franklin Templeton’s six wound up schemes through prepayments, maturities and sales can, by no means, be discounted. However, the narrative needs some course correction here. Returning money to investors without haircuts is not a favour but the bare minimum expected of an AMC. And, by no stretch of imagination, does it give it a clean bill of health with regard to mismanagement and unethical behavior. The other big event of the past fortnight from this newsletter’s point of view was the culmination of the …
Thinly traded listed entities have long served as breeding grounds for stock manipulation, hurting investors. The regulator, the NSE and BSE now want to fix things by focusing on efficient delisting.
The newly announced levy on UPI payments undermines the very foundation of using digital payments for stock market investing. Brokers are in a tizzy.
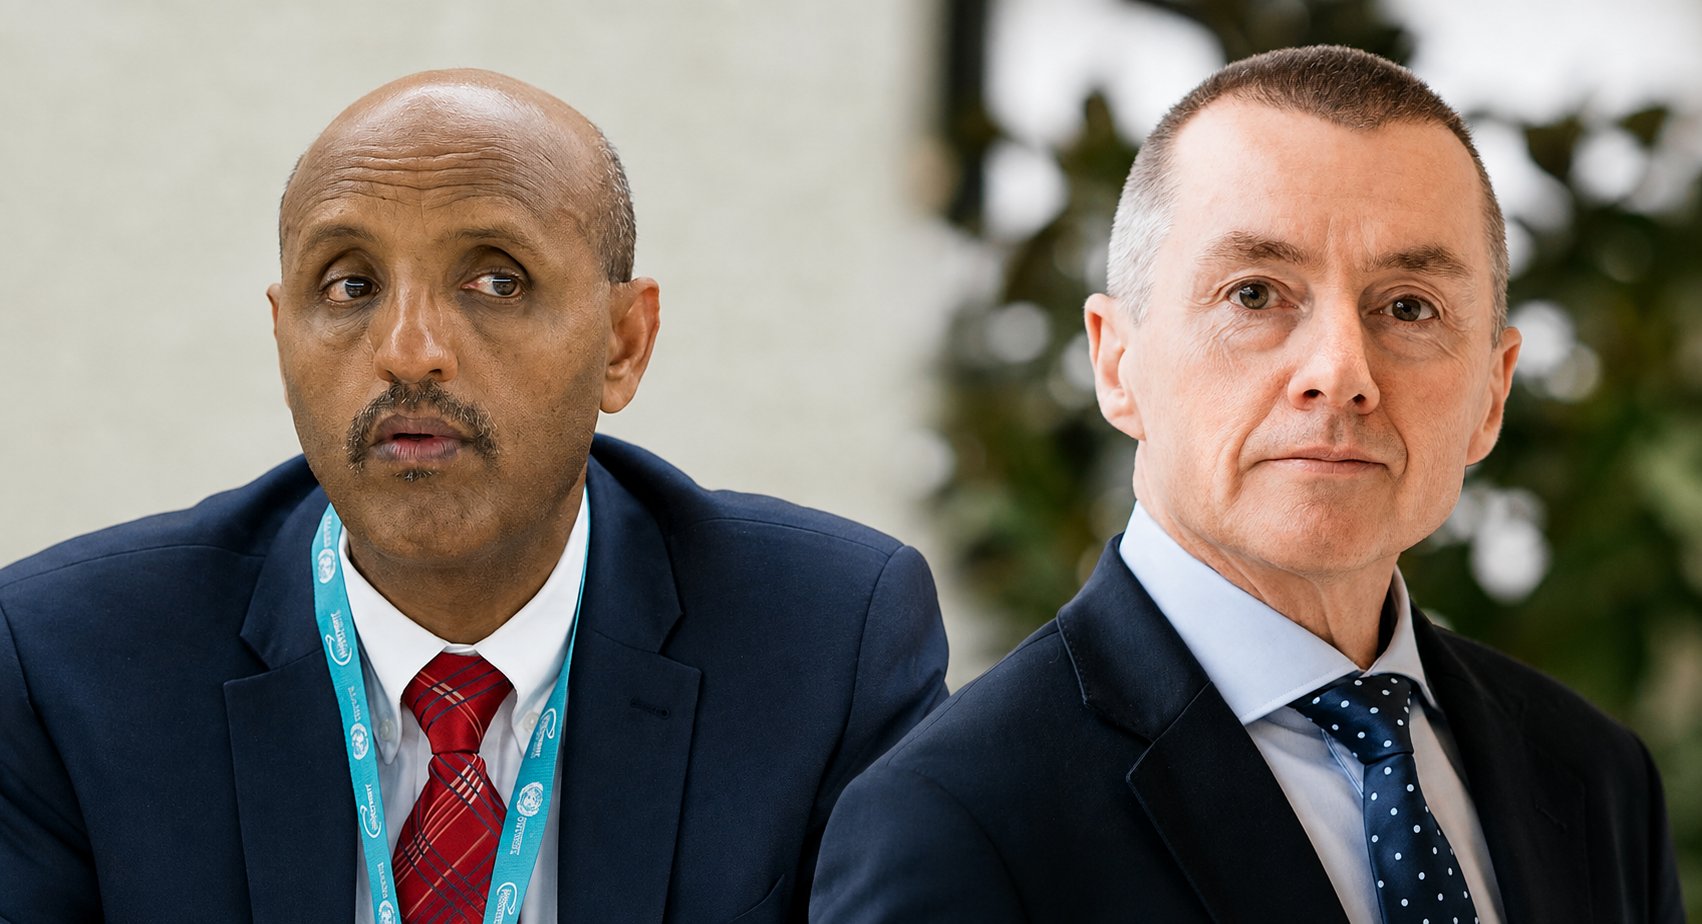
The two new chief executives at Air India and IndiGo come with contrasting reputations but face the same challenge—do their predecessors one better.
Thinly traded listed entities have long served as breeding grounds for stock manipulation, hurting investors. The regulator, the NSE and BSE now want to fix things by focusing on efficient delisting.
The newly announced levy on UPI payments undermines the very foundation of using digital payments for stock market investing. Brokers are in a tizzy.
The two new chief executives at Air India and IndiGo come with contrasting reputations but face the same challenge—do their predecessors one better.