/
•
•
Detailed stories on technology startups, business and economic current affairs.
The fintech’s financial services business has done reasonably well in Q4 FY26. But upping its lending game without the NBFC tag will be a tall task.

India’s fintech companies typically follow a well-defined path: start with payments, offer cashbacks and incentives, launch a variety of products (stockbroking, insurance), partner with banks to grant loans and finally seek a non-banking financial services, or NBFC, licence to lend directly to customers.
Vijay Shekhar Sharma’s Paytm is turning out to be an exception. After the Reserve Bank of India revoked its payment bank licence in April, there has been widespread speculation over whether the Noida-headquartered company would ever get an NBFC licence.
For now, it seems the fintech is not really looking for a licence. “We're not super …
The Delhi-based group lender has been struggling with mounting losses, driven by the shifting priorities of borrowers and the growing pressure on field staff to meet targets.
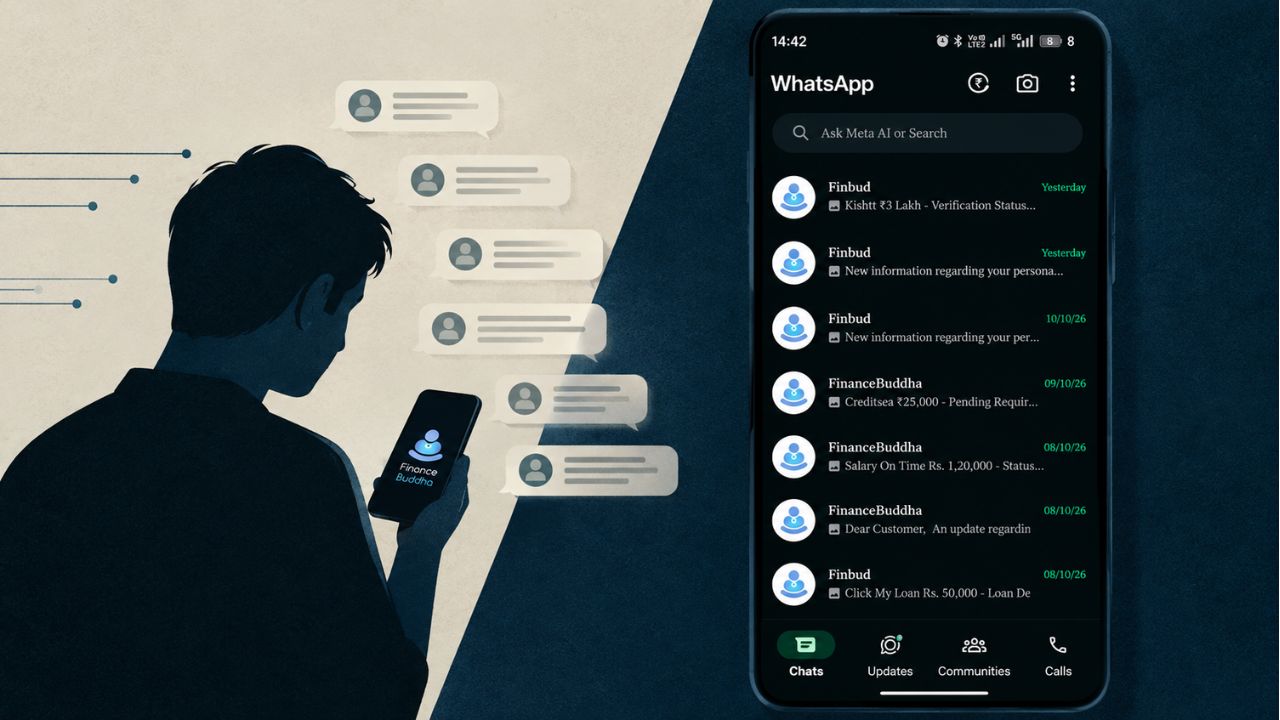
The loan aggregator keeps sending updates on WhatsApp even to users who haven’t applied for a loan. The company is exploiting a grey area in India’s telecom regulatory framework and WhatsApp’s policies.
Its Rs 1,050 crore bet on the five-year-old company—valued at an implied 11.2x revenue multiple and a promoter with baggage—raises serious questions around due diligence.