/
•
•
Detailed stories on technology startups, business and economic current affairs.
The e-commerce platform appears to have put on a good show in FY26, outpacing itself on most fronts. However, the margins tell a different story, one that investors should pay close attention to.

Meesho’s Q4 and full-year FY26 results call for both celebration and concern for the e-commerce platform.
First, the positives. In FY26, the company outpaced itself on almost all fronts compared to the previous fiscal. Its net merchandise value—or NMV, the cumulative checkout value of successfully delivered orders to consumers, including taxes—grew 39% year-on-year to Rs 41,560 crore. Annual transacting users increased by 33% to 264 million; these are unique consumers who successfully placed at least one order on Meesho in the last 12 months. Revenue from operations, too, went up 34% year-on-year, while losses contracted to Rs 1,357.7 crore from …
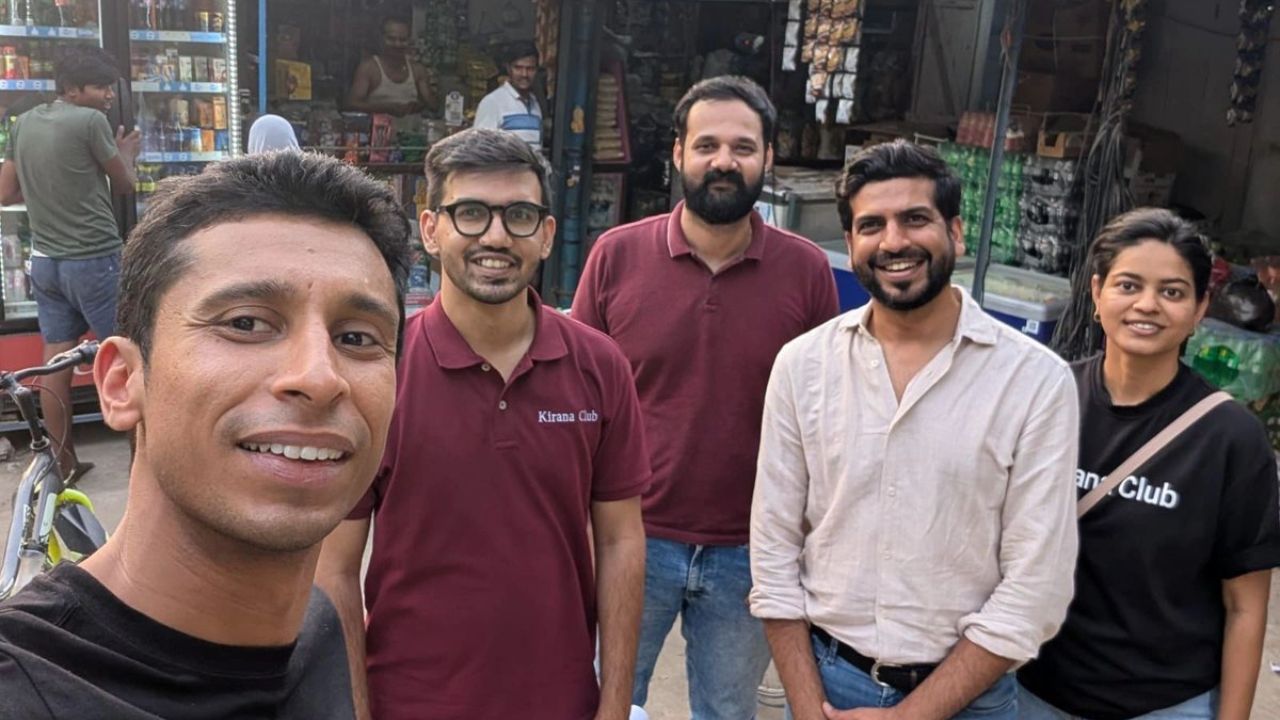
Its acquisition of Kirana Club signals an attempt to find a new growth engine, but grocery retail has been a challenge for even well-funded players.
Online retailers are increasingly realizing that they can manage their own shipments. Where does that leave India’s leading logistics company, which owes much of its growth to the country’s e-commerce sector?
For one of the world’s largest and shrewdest investors to entirely skip putting money in the country is a sign of how quickly the nature of the Indian startup ecosystem has changed.