/
•
•
Detailed stories on technology startups, business and economic current affairs.
Bengaluru-based firm attributes regulatory pushback and a capital crunch as reasons for closing down after four-and-a-half years


Four-and-a-half years into the evolving fintech business and $20 million in funding later, Bengaluru-headquartered Niro has ceased operations, its CEO and co-founder Aditya Kumar announced on Tuesday. He attributed the shutdown to heavy regulation and the company running out of money.
“But sure enough, a perfect storm of regulatory pushback on personal lending, credit deterioration and sub-optimal capitalization forced us to pivot business models (successfully), just as capital ran out,” he said in a post on LinkedIn. “Despite scouring the globe for capital and the country for suitors - I wasn’t able to bring this one home,” he went on …
The Delhi-based group lender has been struggling with mounting losses, driven by the shifting priorities of borrowers and the growing pressure on field staff to meet targets.
The UAE is looking at its first public listing of the year while Egypt just delivered a big one; OpenAI’s bugging accused has ties to Saudi Arabia; and other updates from the week.
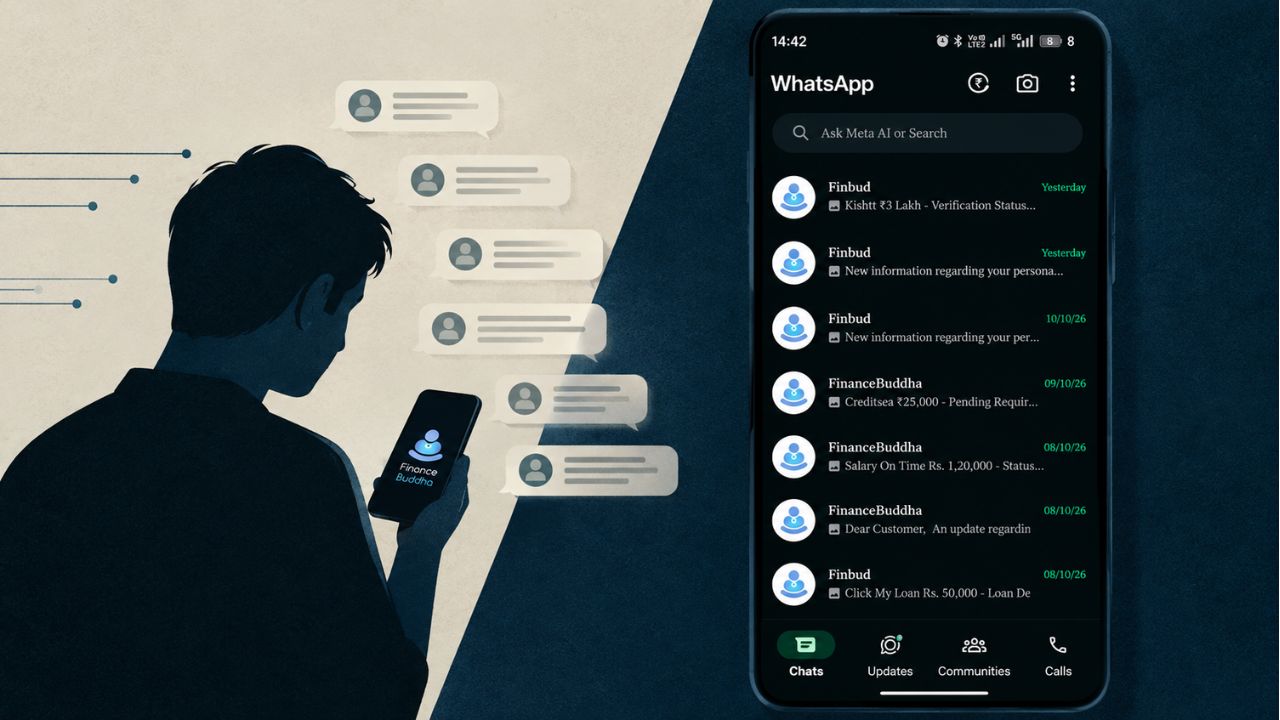
The loan aggregator keeps sending updates on WhatsApp even to users who haven’t applied for a loan. The company is exploiting a grey area in India’s telecom regulatory framework and WhatsApp’s policies.